6 min reading
Poland has a large digital economy with businesses serving customers through e-commerce, online services, technology platforms, and international trade. Crypto can provide an additional payment option where digital assets are relevant to customer demand, transaction patterns, or cross-border operations.
Businesses looking to accept crypto payments in Poland can integrate them through payment gateways, APIs, plugins, or invoicing tools. The appropriate setup depends on the types of payments involved, supported cryptoassets and networks, settlement preferences, and the role of any third-party payment or crypto service providers.
In 2026, crypto-asset services in Poland are subject to the EU Markets in Crypto-Assets Regulation (MiCA), while the national framework for its supervision remains an important regulatory consideration. Businesses should therefore consider both the operational structure of crypto payments and the requirements relevant to the activities performed by the merchant and its providers.
Crypto payments for businesses in Poland
Poland has a substantial e-commerce and digital services market, with businesses serving customers through online stores, marketplaces, technology platforms, and other digital channels. In this environment, crypto payments may provide an additional option where they are relevant to customer demand, international transactions, or the company's business model.
Businesses can accept supported cryptoassets alongside cards, bank transfers, digital wallets, and other payment methods. The suitability of crypto depends on factors such as supported assets and networks, transaction costs, settlement arrangements, refunds, accounting, and operational requirements.
For e-commerce companies and digital service providers, crypto may be integrated into checkout or invoicing workflows. Businesses serving customers across different markets may also evaluate crypto for supported cross-border payments while comparing transaction costs, currency conversion, settlement terms, and reconciliation with their existing payment methods.
Marketplaces, SaaS companies, and other online businesses may consider crypto where it fits their payment flows and customer base. For fintech companies and other financial businesses, additional regulatory considerations may apply depending on the crypto-asset services involved.
Businesses using third-party crypto payment providers should also consider the provider's role in the transaction, supported assets and networks, and settlement and custody arrangements.
Legal status of crypto payments in Poland
Cryptoassets are not legal tender in Poland in the same way as the Polish złoty, but businesses may accept supported cryptoassets as payment. The regulatory requirements that apply depend on the activities performed by the business and the role of any third-party crypto service providers involved.
The EU Markets in Crypto-Assets Regulation (MiCA) applies directly in Poland and establishes requirements for crypto-asset service providers and other activities within its scope. Poland's transitional period for providers operating under the previous national framework ended on 1 July 2026. Registration in the Polish Register of Virtual Currency Activities no longer authorises an entity to provide services regulated under MiCA.
Poland's national framework for implementing and supervising MiCA remains relevant to the regulatory landscape. A national Crypto-Assets Market Act adopted by parliament in 2026 was vetoed and was not subsequently passed again by the Sejm. As a result, no Polish public authority had been formally designated as the competent authority for most MiCA activities, including supervision of crypto-asset service providers, although the KNF retains specific responsibilities in areas including electronic money token issuers.
Accepting cryptoassets as payment for a business's own goods or services should be distinguished from providing regulated crypto-asset services such as custody, exchange, transfer, or operation of a crypto-asset trading platform. Whether additional regulatory requirements apply depends on the activities performed and the structure of the payment arrangement.
Businesses using third-party crypto service providers should consider whether the provider holds the appropriate MiCA authorisation to perform the relevant services. Providers authorised in another EU Member State may be able to provide services across the EU in accordance with MiCA passporting requirements.
How to accept crypto payments in Poland
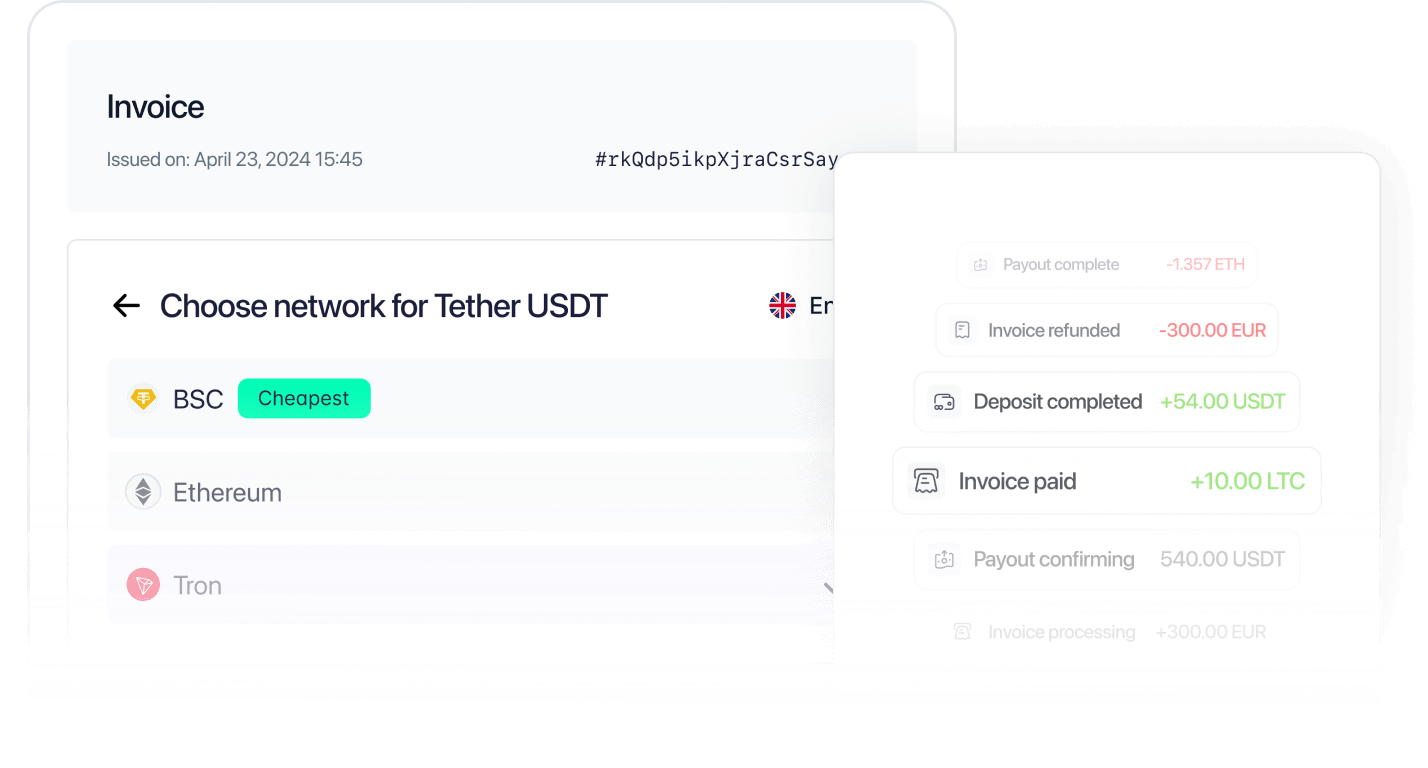
Businesses looking to accept crypto payments in Poland can use a crypto payment gateway or integrate payment functionality through APIs, plugins, or invoicing tools. The appropriate setup depends on the business model, existing payment infrastructure, supported cryptoassets and networks, and settlement requirements.
Customers may pay using Bitcoin, stablecoins, or other supported cryptoassets, depending on the provider and applicable requirements. Businesses may retain supported digital assets or use conversion services to settle payments in Polish złoty, euros, or another supported currency where available. Payment records should be incorporated into appropriate accounting and reconciliation processes. Businesses should consider how crypto payments are recorded, valued, converted, refunded, and matched with customer or invoice data, as well as any tax or reporting requirements relevant to their activities.
When selecting crypto payment infrastructure, businesses should evaluate supported assets and networks, custody arrangements, security, conversion and settlement options, reporting functionality, and the role of the providers involved.
Fees and settlement
The cost of accepting crypto payments in Poland depends on the payment provider, cryptoasset, blockchain network, transaction structure, and settlement model. Businesses may encounter network fees, provider fees, custody-related costs, and conversion charges where incoming cryptoassets are exchanged for Polish złoty, euros, or another supported currency.
Settlement arrangements vary between providers. Businesses may retain supported cryptoassets or use conversion services to receive fiat currency where available. Settlement timing, exchange rates, conversion terms, network confirmation requirements, and custody arrangements should be considered when comparing payment setups.
Stablecoins may reduce exposure to price volatility relative to non-pegged cryptoassets, but their suitability depends on the specific asset, network, provider, liquidity, and settlement requirements. Businesses should also consider the regulatory treatment of the cryptoassets and services involved.
Blockchain transactions provide an on-chain record of transfers, but businesses may still need to determine the appropriate value of transactions for accounting purposes and connect payment data with invoices, customers, refunds, conversion records, and other internal systems. Reconciliation and reporting should therefore be considered as part of the overall payment workflow.
Businesses should compare the total cost and settlement structure of crypto payments with their existing payment methods rather than assuming that crypto will always provide lower fees, faster settlement, or simpler processing.
Use cases in Poland
Crypto payments may be relevant to businesses in Poland operating in e-commerce, digital services, SaaS, marketplaces, fintech, professional services, and other sectors serving domestic or international customers. Their suitability depends on customer demand, transaction patterns, supported cryptoassets and networks, and the company's payment and settlement requirements.
E-commerce businesses and online platforms may offer crypto alongside cards, bank transfers, digital wallets, and other payment methods. Digital service and SaaS companies may also integrate crypto into checkout, billing, or invoicing workflows where supported by their payment infrastructure. Marketplaces may consider crypto for transactions involving customers, sellers, or service providers across different markets. Professional and export-oriented digital businesses working with international clients may similarly evaluate crypto for supported cross-border payments while comparing transaction costs, conversion requirements, settlement terms, accounting, and reconciliation with their existing payment methods.
Fintech companies may incorporate crypto payment functionality into their products or payment workflows where appropriate. Businesses performing activities beyond merchant payment acceptance should assess whether those activities constitute regulated crypto-asset services and require appropriate authorisation.
What businesses should consider
Businesses evaluating crypto payments in Poland should consider how the payment method fits their existing operations, including supported cryptoassets and networks, settlement and conversion options, transaction costs, accounting, reconciliation, and the role of third-party providers. Because MiCA applies to regulated crypto-asset services and Poland's transitional period ended in July 2026, businesses should also consider the regulatory status and appropriate authorisation of providers involved in their payment structure.
Disclaimer: This guide is provided for general informational purposes only and does not constitute legal, regulatory, or financial advice. Regulatory requirements may vary depending on the jurisdiction and specific circumstances.